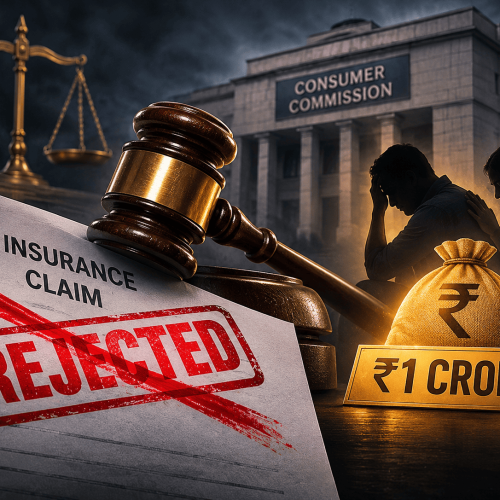
The District Consumer Disputes Redressal Commission-I, Jodhpur, has directed PNB MetLife India Insurance Company Ltd to pay ₹1 crore in life insurance benefits to a policyholder’s husband after finding that the insurer wrongly rejected his wife’s death claim.
The commission held that the insurer failed to establish that the alleged non-disclosure of pre-existing health conditions had any connection with the policyholder’s death. The order also includes interest, compensation for mental agony, and litigation expenses. The case highlights the importance of proper medical disclosures, transparent policy proposal forms, and evidence-based claim investigations in India’s life insurance industry.
What Happened in the PNB MetLife Insurance Claim Case?
The complaint was filed by Narendra Singh Shekhawat after PNB MetLife rejected the death claim of his wife, Kiran. She purchased a 34-year MetLife Mera Term Plan on July 28, 2020, with an annual premium of ₹18,288 and a sum assured of ₹1 crore. Kiran died at AIIMS Jodhpur on March 28, 2023, following complications arising from a brain tumour. However, when her husband filed the insurance claim, PNB MetLife rejected it on June 25, 2023, alleging non-disclosure of pre-existing health conditions.
The insurer claimed that Kiran had a history of irregular menstruation and easy fatigability for approximately five years before purchasing the policy. It relied on its investigation and medical records to support the rejection. The policyholder’s husband subsequently approached the consumer commission, challenging the insurer’s decision.
Why Did the Consumer Commission Rule Against PNB MetLife?
The commission examined the insurance proposal form, medical records and the insurer’s justification for rejecting the claim. It identified two important shortcomings in the insurer’s defence:
1. The proposal form did not specifically ask about the alleged conditions
The commission observed that the online insurance proposal form did not specifically ask about irregular menstruation or easy fatigability. Therefore, the insurer’s allegation of non-disclosure could not be established merely by referring to these conditions after the policyholder’s death.
2. Insufficient evidence of prior medical treatment
The insurer failed to produce documentary evidence establishing that Kiran had received treatment for these conditions before purchasing the insurance policy. The commission also noted that her medical records attributed her death to septic shock, aspiration pneumonitis and complications following surgery for a pituitary macroadenoma. The insurer could not establish a direct connection between the alleged undisclosed conditions and her death.
Considering these findings, the commission held that rejecting the claim amounted to a deficiency in service.
What Has the Commission Ordered?
The District Consumer Disputes Redressal Commission-I, Jodhpur, directed PNB MetLife to comply with the following:
- Insurance benefit: ₹1 crore to the policyholder’s husband.
- Interest: 6% annual simple interest on the insured amount from the date of filing the consumer complaint until payment.
- Compensation: ₹50,000 for mental agony.
- Litigation expenses: ₹25,000.
The insurer has been given two months to comply with the order. The total fixed compensation, excluding interest, amounts to ₹1.0075 crore.
Key Lessons for Life Insurance Companies
The order highlights several operational and compliance considerations for life insurers.
1. Review insurance proposal forms
Proposal forms should clearly capture relevant medical information. Insurers must ensure that questions are specific, understandable, and sufficient for assessing the applicant’s health disclosures.
2. Strengthen medical underwriting
Underwriting teams should maintain proper documentation of medical assessments, additional information requests, and decisions taken while issuing policies.
3. Ensure evidence-based claim investigations
Claim rejection decisions should rely on verifiable medical records and relevant evidence. Investigations should establish whether the alleged non-disclosure is material to the claim.
4. Improve claims governance
Insurers should maintain documented reasons for claim repudiation, ensure appropriate internal reviews, and establish clear escalation mechanisms for disputed claims.
5. Strengthen consumer grievance redressal
A transparent grievance redressal mechanism can help insurers address disputes at an early stage and reduce the risk of prolonged consumer litigation.
Implications for India’s Insurance Sector
The Jodhpur consumer commission’s order reinforces an important principle for the insurance industry: allegations of non-disclosure must be supported by adequate evidence, and claim repudiation decisions must be based on the policy terms and relevant facts.
For life insurers, this case highlights the need to align customer onboarding, medical underwriting and claims assessment processes. As India’s life insurance market expands, maintaining policyholder confidence will depend on transparent disclosures, consistent underwriting practices and fair claim settlement procedures. For insurers, effective claims governance is not limited to meeting regulatory requirements. It is also essential to protecting customer trust and reducing legal and reputational risks.