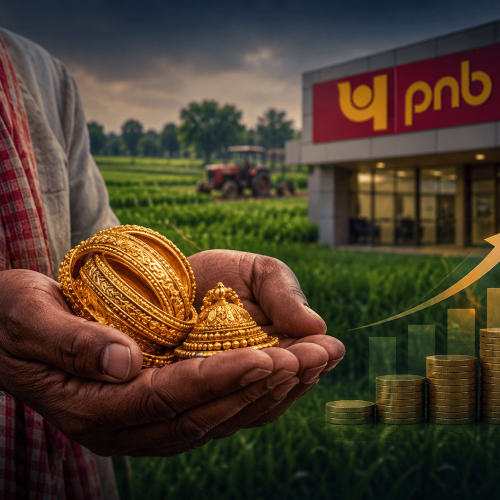
Punjab National Bank (PNB) is planning a significant expansion of its agricultural gold loan portfolio, targeting ₹60,000 crore by FY27 against its current portfolio of approximately ₹37,000 crore. The move forms part of the bank’s broader strategy to strengthen its retail, agriculture, and MSME (RAM) lending business, improve priority sector lending (PSL) performance, and increase overall profitability. Alongside its agricultural lending expansion, the public sector lender is focusing on improving core operating profit, increasing lending yields and reducing exposure to lower-yielding corporate loans.
The developments come as PNB reported its highest-ever quarterly net profit of ₹5,532 crore in Q2 FY27, registering 13% year-on-year growth.
Agricultural Gold Loan Portfolio to Reach ₹60,000 Crore
PNB aims to increase its agricultural gold loan book from approximately ₹37,000 crore to ₹60,000 crore by FY27, representing growth of nearly 62%. The expansion is expected to strengthen the bank’s priority sector lending position and reduce its dependence on purchasing Priority Sector Lending Certificates (PSLCs) to meet regulatory targets. PNB also aims to become a net seller of these certificates over the longer term.
Agricultural gold loans allow farmers to access credit by pledging gold ornaments as collateral. For banks, this segment provides an opportunity to expand secured lending while supporting agricultural credit requirements. PNB’s strategy also reflects the growing importance of gold-backed lending in India’s financial services market, where banks and NBFCs are competing to expand their presence in secured retail credit.
RAM Portfolio Drives Credit Growth
PNB is placing greater emphasis on its Retail, Agriculture and MSME segments, which currently account for approximately 54% of its total advances.
The bank has reported strong growth across these segments:
- MSME advances: Approximately 20% year-on-year growth.
- Agricultural priority sector lending: Approximately 18% growth.
- Core retail advances: Approximately 16.3% growth.
PNB is targeting overall loan book growth of 12–13% in FY27, supported by continued demand across these lending segments. The bank’s deposit base also recorded 15.6% growth in September 2026. Its credit-deposit ratio of approximately 74% provides additional room to expand lending operations.
This shift towards retail, agriculture, and MSME lending is expected to improve portfolio diversification and support better lending yields.
PNB Targets ₹6,000 Crore Quarterly Net Profit
PNB is also targeting further improvement in quarterly profitability after reporting a net profit of ₹5,532 crore in Q2 FY27. According to Managing Director and CEO Ashok Chandra, the bank expects to move towards the ₹6,000 crore quarterly profit level over the coming quarters, supported by sustained growth in operating profit.
One of the important indicators is the bank’s core operating profit, which grew approximately 29% year-on-year in Q2 FY27. This performance is particularly significant because the bank faced a decline in treasury income during the quarter. Treasury income fell to ₹753 crore in Q2 FY27 from ₹1,769 crore in the corresponding quarter of the previous year. Despite this decline, PNB maintained growth in operating profit, highlighting the contribution of its core lending and banking operations.
Focus on Higher Lending Yields and Net Interest Margins
PNB is restructuring its corporate loan portfolio by reducing exposure to lower-yielding advances while continuing to pursue fresh lending opportunities in sectors such as renewable energy and data centres. The bank is targeting a 40–45 basis-point improvement in its blended corporate loan yields from the earlier level of 7.28%.
It also expects net interest margin (NIM) improvement in the December 2026 quarter:
- Global NIM: Expected improvement of 7–8 basis points.
- Domestic NIM: Expected improvement of 9–10 basis points.
However, an anticipated 7–8 basis-point increase in the cost of deposits could partially offset these improvements. The bank is also working to reduce its cost-to-income ratio from approximately 50% to 49% by March 2027, with a longer-term target of around 45%.
Asset Quality and Expected Credit Loss Provisioning
Improving asset quality remains another important part of PNB’s profitability strategy.
In Q2 FY27, the bank reported:
- Gross NPA ratio: 2.55%.
- Net NPA ratio: 0.25%.
- Provision Coverage Ratio (PCR): Approximately 97.3%.
PNB estimates its gross Expected Credit Loss (ECL) provisioning requirement at approximately ₹8,000 crore. The bank has already built additional provisions of ₹2,560 crore against NPA accounts and around ₹1,100–1,150 crore against standard accounts. The bank expects normalised credit costs of approximately 25–30 basis points, including the anticipated impact of ECL-related provisioning. PNB is also targeting a Return on Assets (RoA) of approximately 1.1% by FY28, supported by better core profitability, fee-based income and improved lending yields.
What This Means for the Banking and NBFC Sector
PNB’s strategy highlights three important trends in India’s lending market.
1. Growing importance of secured lending: Agricultural gold loans are becoming an important growth segment for financial institutions. Banks and gold loan NBFCs can benefit from demand for collateral-backed credit, particularly in rural and semi-urban markets.
2. Greater focus on portfolio profitability: Loan growth alone is no longer the only priority. Financial institutions are increasingly reviewing portfolio yields, funding costs, and asset quality to improve overall profitability.
3. Priority sector lending as a business opportunity: Expanding direct agricultural and MSME lending can help banks meet PSL requirements while reducing their dependence on PSLC purchases.
For NBFCs operating in the gold loan and rural lending segments, PNB’s expansion plans also indicate increasing competition from public sector banks.
As banks strengthen their secured lending portfolios and improve their reach in underserved markets, NBFCs will need to focus on customer experience, faster credit delivery, responsible lending practices, and efficient risk management to maintain their market position.
PNB’s FY27 strategy ultimately reflects a broader shift in the banking sector towards granular lending, better portfolio yields and sustainable profitability.